Breaking down the OBBBA compliance updates that every tax team should be ready to explain
Highlights
- Several OBBBA tax breaks are now permanent, including 100% bonus depreciation and the QBI deduction.
- OBBBA deadlines vary by provision, with some expiring after 2028 and others lasting until 2030.
- Some 2027 OBBBA questions remain unresolved, requiring documented tax positions where guidance is unclear.
Many tax clients perceive the One Big Beautiful Bill Act (OBBBA) as a singular tax law with one deadline. But you know better. Some OBBBA tax changes are now permanent. Others expire at different dates, and a few questions still don’t have settled answers under current IRS compliance updates. It’s up to your team to clear up any misunderstandings your clients might have ahead of the April deadline.
Here are the tax changes for 2027 that clients are most likely to get wrong, and what tax teams should have ready before those conversations start.
Jump to ↓
1. Some clients think every OBBBA provision is temporary
2. Some clients think the temporary provisions all expire on the same date
3. Clients assume every open tax question already has an answer
4. Clients think a bigger deduction is automatically a bigger tax benefit
5. Clients assume related entities are automatically excluded from new deductions
How does the OBBBA affect the 2027 filing season?
1. Some clients think every OBBBA provision is temporary
Several permanent tax law changes support multi-year tax planning, not a one-time adjustment:
- Bonus depreciation, restored to 100% for acquisitions after January 19, 2025
- Section 179 expensing, now capped at $2.5 million with a $4 million phase-out threshold, both indexed
- The qualified business income deduction
- The standard deduction, child tax credit, and adoption credit
Clients who treat permanent provisions as short-term wins often miss the entity structure and capital planning decisions that follow. If a deduction isn’t going away, the tax planning conversation shifts from “use it before it’s gone” to “build around it.”
2. Some clients think the temporary provisions all expire on the same date
They don’t. Each OBBBA deadline runs on its own clock:
- Tips, overtime, and car loan interest deductions run through 2028
- The SALT deduction cap, raised from $10,000 to $40,000, steps back down to $10,000 in 2030
- Qualified production property has a two-part window: construction must begin before 2029, and the property has to be placed in service before 2031
Scoping a client’s tax planning strategy to a single “OBBBA deadline,” instead of the date attached to each specific provision, is one of the more common errors in current tax compliance guidance.
3. Clients assume every open tax question already has an answer
Some OBBBA provisions raise questions the statute doesn’t resolve, and IRS guidance for 2027 hasn’t caught up on all of them. The 529 plan timing issue is a good example: the expanded K-12 definitions apply to distributions taken after July 4, 2025, but the statute doesn’t say whether the expense itself has to be incurred after that date too.
When that happens, there are two different problems, and they call for different research methods:
| Situation | What it means | What helps |
|---|---|---|
| “We don’t know” | The answer exists, you haven’t found it yet | More research |
| “It’s complicated” | No statute, no regulation, no case law addresses it directly | A method for building a defensible position |
For the second category, more searching won’t necessarily help. Here’s what does:
- State the question precisely (not “how do the 529 changes work,” but “does the expense have to be incurred after the effective date, or only the distribution?”)
- Review every available tax authority, including what turns out not to be authority (proposed regulations and their preambles don’t count)
- Check whether analogous IRS guidance applies (HSA rules, for instance, treat the date an expense was incurred as irrelevant once the account exists)
- Land on a position standard, either substantial authority or reasonable basis with disclosure on Form 8275, and document the reasoning
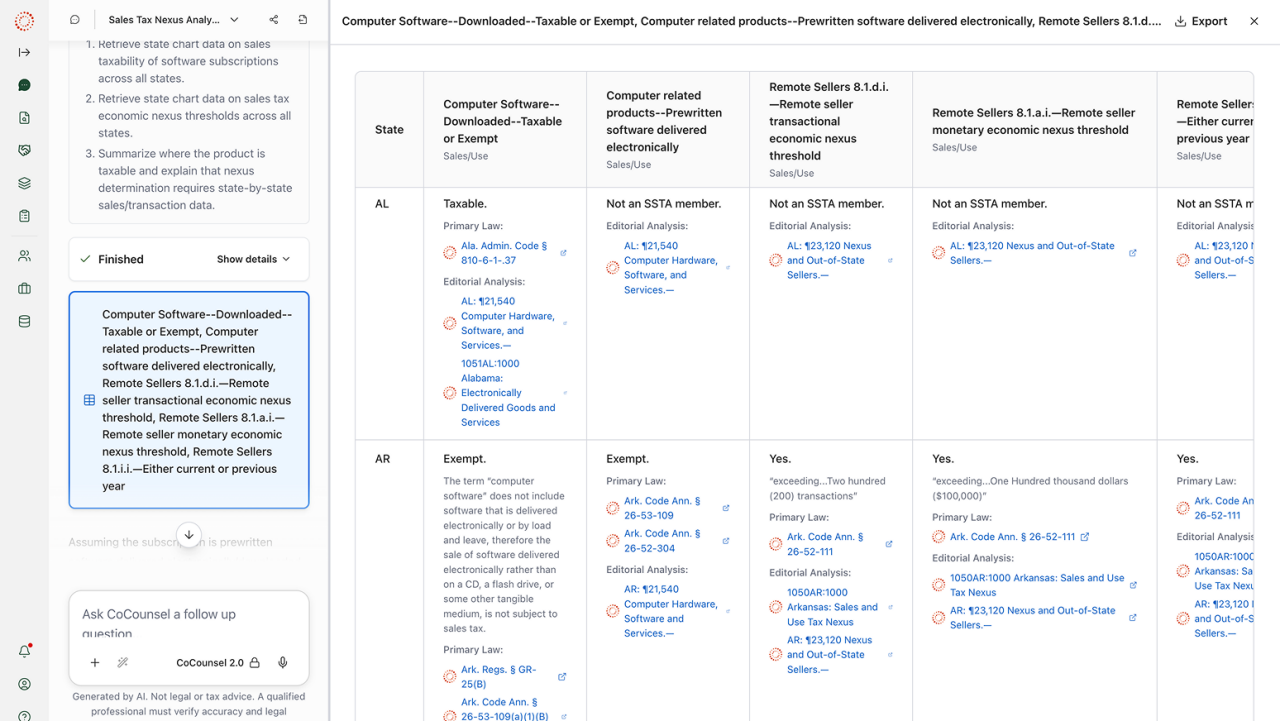
Get instant expertise with CoCounsel Tax
Reduce research time and increase confidence with simplified, citation-backed answers to your most complex tax question
Watch webinar ↗4. Clients think a bigger deduction is automatically a bigger tax benefit
The SALT cap increase showcases the starkest contrast between tax compliance versus tax advisory. Entered on a return, it’s a single line. As a client tax planning question, it involves the deduction amount, the 2030 sunset, the documentation standard, and a plan for what happens if IRS guidance shifts before then. Clients who only see the number on the return miss the timing decisions attached to it.
5. Clients assume related entities are automatically excluded from new deductions
The qualified production property deduction raises this for clients with related operating and holding entities. Current IRS guidance holds that commonly owned property isn’t “leased,” and a substantial transformation test determines what counts as a qualified product.
The election also isn’t all-or-nothing: a client can elect any amount up to the unadjusted depreciable basis. That flexibility is easy to miss if tax return analysis stops at “does this qualify.”
How does the OBBBA affect the 2027 filing season?
OBBBA compliance updates have increased return complexity across the board. The provisions above are exactly where that complexity concentrates, and they’re the ones most likely to prompt client questions after filing rather than before.
If your team wants a closer look at how these OBBBA provisions and IRS compliance updates are shaping up heading into 2027, our on-demand webinar goes further in depth on where guidance stands now, which tax questions remain open, and how to scope client conversations around the deadlines that actually apply.
WEBINAR: OBBBA one year in: The guidance and changes your tax & accounting firm needs to know
A year after the One Big Beautiful Bill Act rewrote major parts of the tax code, the picture is finally clear enough to plan around. This session gives you a practical framework for turning OBBBA's structure into planning opportunities and advisory revenue.
Watch webinar ↗